Auto
When a teen driver joins your household
Insurance premiums spike when a teen starts driving. A few moves can take the sting out without sacrificing coverage.
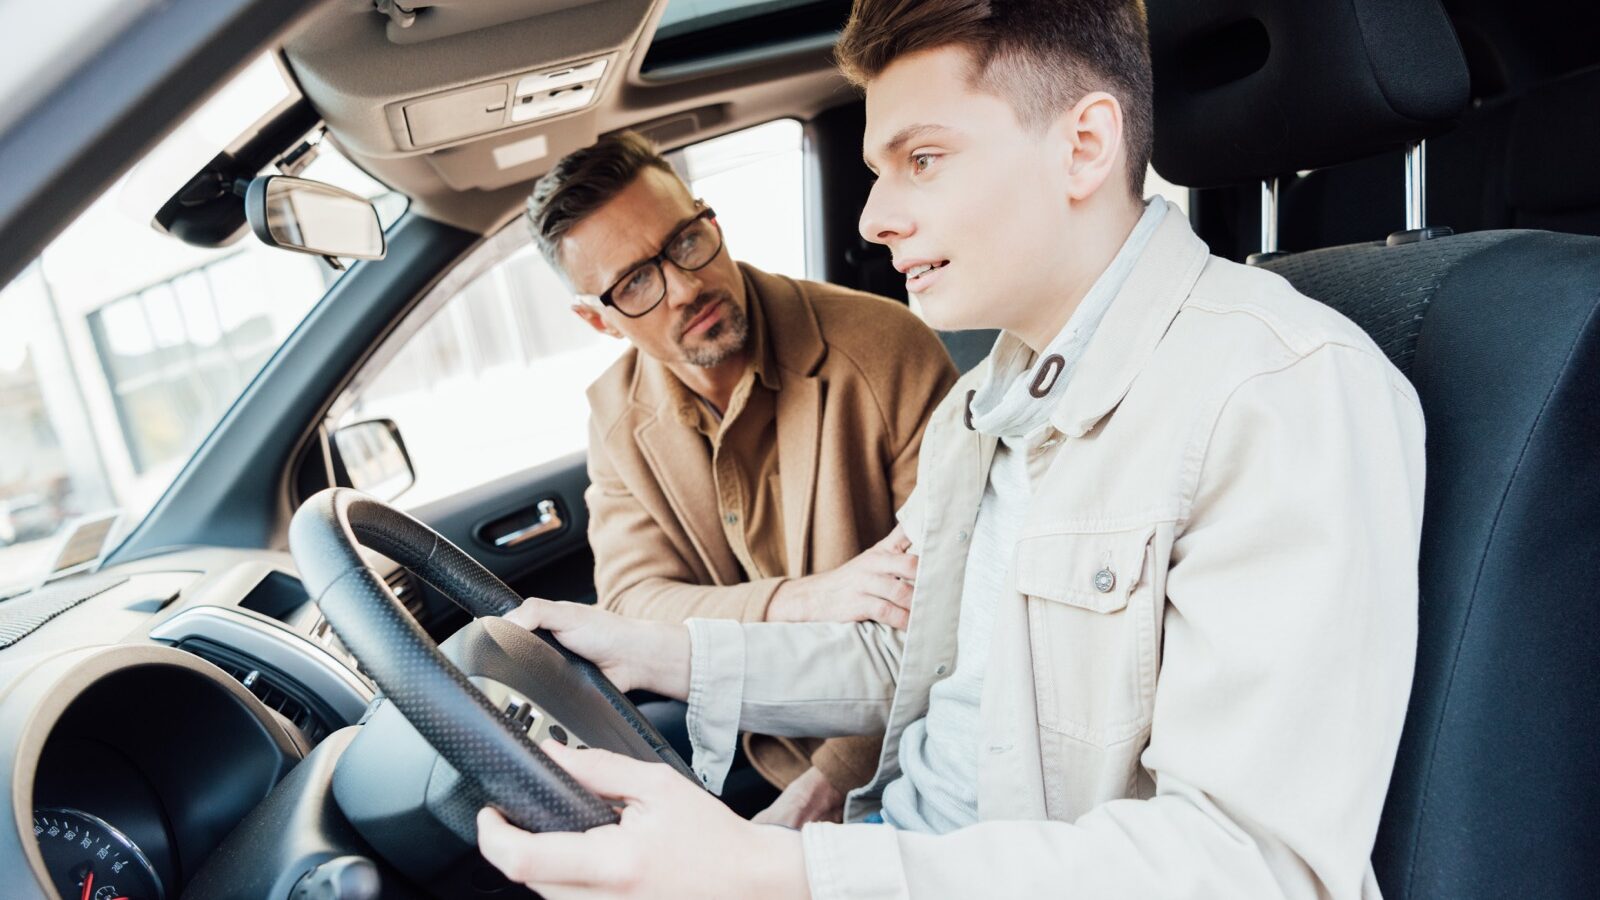
Adding a teen to your auto policy is expensive, and there’s no way around it. But how expensive depends on a handful of choices made in the months before and after they start driving. Here’s what we tell households walking through this.
Before they drive
- Take a driver-training course. Most carriers offer a discount (typically 5–15%) for completing an approved course, and some states reduce the probationary-licensing period.
- Grades matter. “Good student” discounts usually require a 3.0 GPA and apply through college graduation. Keep the transcript handy.
- Decide which car they’ll primarily drive. Rating rules vary: some states let you list a teen as occasional driver on the oldest, lowest-value car. Others rate the youngest driver on the most expensive vehicle by default.
Adding them to your policy
When you call, have their permit or license number, any driver-training certificate, and a rough estimate of annual mileage. Carriers rate teens very differently from one another, so shopping quotes matters more at this stage than at almost any other.
Discounts worth asking about
- Good-student discount (3.0+ GPA)
- Driver-training course discount
- Distant-student discount (if they’ll be away at college without a car)
- Usage-based / telematics programs that track driving behavior, often meaningful savings for safer drivers
A note on liability
Teen drivers cause more severe accidents on average. If you haven’t already raised your liability limits, this is the moment. A single serious claim can outrun a 100/300 limit quickly. Stacking an umbrella policy on top is a cheap add-on for the exposure.
We walk through each of these questions on first calls with households adding a teen driver. Get a quote, or check your auto coverage before you call.