Flood
Flood zones: why FEMA maps don’t tell the whole story
Most flood claims come from homes outside high-risk zones. Here's what to know about flood coverage even if your mortgage doesn't require it.
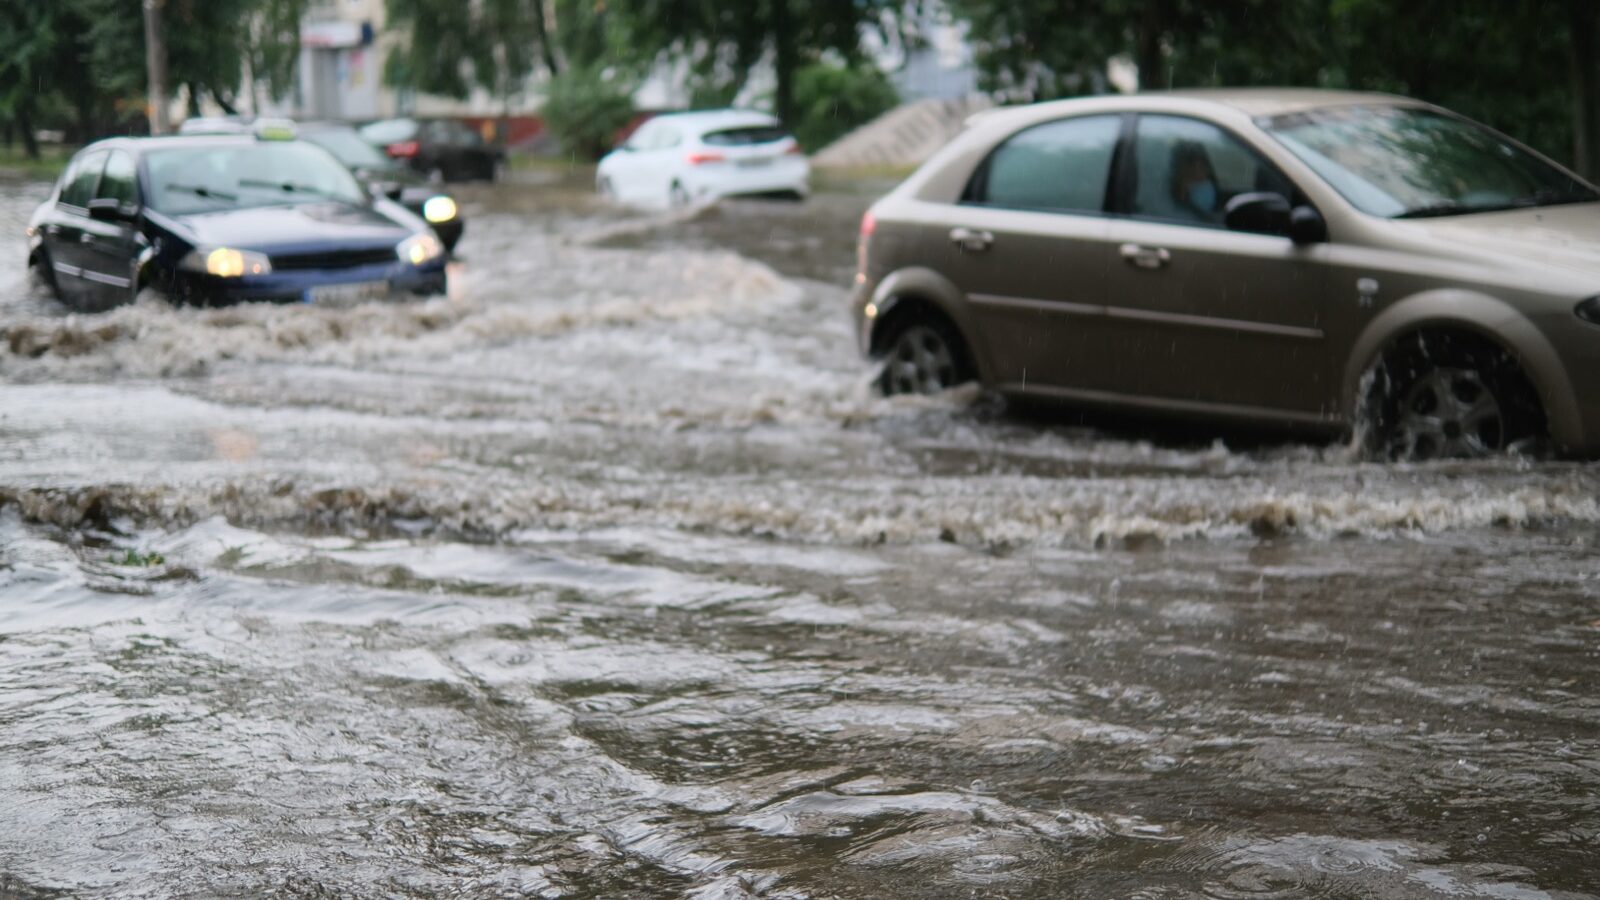
Most flood claims come from homes outside high-risk flood zones. The FEMA maps tell you where flooding is most likely, not where it’s possible. Here’s what to know before your next renewal.
Reading a FEMA map
FEMA classifies properties into flood hazard zones. Zones A and V are “high risk” and usually trigger a mortgage lender’s flood insurance requirement. Zones B, C, and X are “moderate to low risk”, but they’re not no-risk.
You can look up your property at msc.fema.gov. Map updates happen infrequently; a parcel that was zone X ten years ago may be higher risk today based on new hydrology studies or changes in the surrounding watershed.
What standard homeowners insurance covers
Nothing, when it comes to flood. Standard policies exclude “flood” specifically: rising groundwater, storm surge, or overflow from a body of water. Wind-driven rain that comes through a damaged roof can be covered under the windstorm section of a home policy. Water that comes up through the floor is not.
NFIP versus private flood
The National Flood Insurance Program (NFIP) is the default in most areas. It caps dwelling coverage at $250,000 and contents at $100,000, with limits on basement coverage and specific exclusions.
Private flood policies can offer higher limits, replacement-cost coverage on contents, and sometimes shorter waiting periods. In Florida and parts of coastal New York, private flood is often both cheaper and broader. Worth comparing side-by-side.
The 30-day waiting period
Most new flood policies don’t take effect until 30 days after purchase. Buying after a storm forms is usually too late. Plan ahead, ideally at policy renewal or when you close on a new home.
If you’re unsure whether flood makes sense at your address, we can pull your zone, compare NFIP and private options, and walk through the specific exclusions. Start here.